Can You Get a Mortgage With Bad Credit?
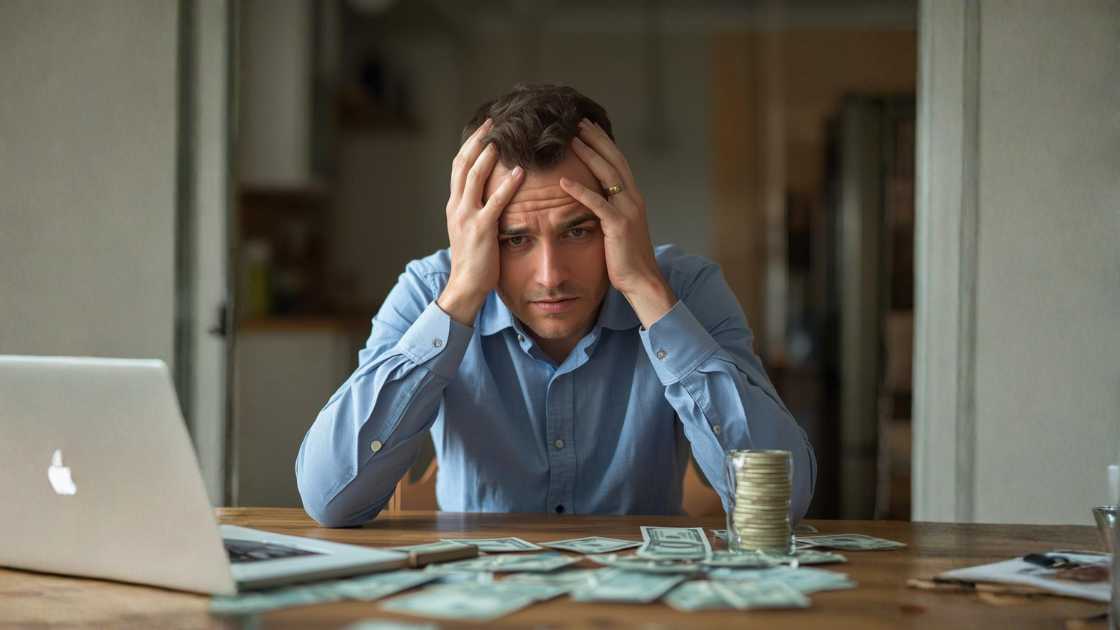
Having bad credit does not automatically mean you cannot get a mortgage in the UK. What matters is the type of credit issue, how recent it is, whether it has been resolved, and how the rest of your application looks today.
A missed payment from several years ago may be assessed very differently from recent arrears, an active debt arrangement or multiple unresolved defaults.
This guide explains how bad credit can affect a mortgage application, what lenders may look at, and when it may be worth speaking to a specialist mortgage adviser before applying.
What “Bad Credit Mortgages” Actually Are
There is no single mortgage product officially labelled as a “bad credit mortgage” across the UK market. The term is commonly used to describe mortgage options available to borrowers whose credit history includes adverse markers.
These markers may include missed or late payments, defaults, or other negative entries recorded on a credit file. Because these signals increase perceived risk, many mainstream high-street lenders apply tighter restrictions or decline applications outright.
As a result, bad credit mortgages often come with trade-offs such as higher interest rates or larger upfront contributions. These features reflect how lenders price risk rather than a punishment for past mistakes.
How Bad Credit Is Assessed in Real Life (Not in Theory)
From a lender’s perspective, bad credit is not assessed in isolation. It’s evaluated as part of a broader risk picture.
From the borrower’s perspective, this is where expectations often differ.
Lenders look at your credit file to understand patterns rather than just individual events. A single historical issue may be treated very differently from repeated recent problems. Timing, severity, and behaviour since the issue occurred all matter.
Specialist lenders tend to take a more holistic approach. Alongside credit history, they consider income stability, affordability, existing commitments, and how much financial buffer you have. This is why two applicants with similar credit issues can receive very different outcomes.
Who Bad Credit Mortgages Are Actually For (And Who They Aren’t)
Typically suitable for:
Applicants with older or resolved credit issues
Borrowers with stable, provable income
Buyers who can contribute a larger upfront amount
Those who have improved their financial behaviour over time
Often unsuitable if:
Credit issues are recent and ongoing
Income is unstable or difficult to evidence
Affordability is already stretched
Expectations are based on standard high-street mortgage terms
This filtering matters. Knowing early whether you fall into the first or second group can save time and avoid unnecessary credit damage.
Not sure how your credit history may affect your mortgage options?
See our Bad Credit Mortgage service for a more detailed look at lender criteria, deposits, credit events and preparing an application.
What Most Buyers Miss (But Shouldn’t)
One misconception:
Bad credit doesn’t mean “no options”, but it almost always means “different conditions”.
One risk factor:
Applying to the wrong lender can lead to repeated declines, which may worsen your credit profile and reduce future options.
One long-term impact:
Taking a mortgage without a clear exit or improvement plan can leave you locked into less favourable terms for longer than expected.
This is why strategy matters just as much as eligibility.
Risks, Costs, and Trade-Offs
Bad credit mortgages usually involve compromises.
Interest rates may be higher than standard products. Flexibility can be limited, and fewer lenders may be willing to offer terms. In some cases, affordability assessments are stricter to ensure the mortgage remains sustainable even under pressure.
None of these factors automatically make the option “bad”. But ignoring them often leads to disappointment later.
Common Questions Buyers Ask
Can you really get a mortgage with bad credit?
In some cases, yes. But it depends on the type, timing, and severity of the credit issues.
Is it riskier if my credit problems are recent?
Generally, recent issues raise more concern than older, resolved ones.
Why do some people fail even when they earn well?
Because income alone doesn’t offset unstable credit behaviour or affordability pressure.
Is it still possible today?
Availability depends on current lender criteria, which can change over time.
Should You Consider a Bad Credit Mortgage?
A bad credit mortgage can make sense if your credit issues are behind you, your income is stable, and you understand the trade-offs involved.
It can be risky if expectations are unrealistic or if the decision is rushed without a longer-term plan. Often, the outcome comes down to timing, lender choice, and preparation rather than credit score alone. This topic often overlaps with other mortgage eligibility factors, such as income structure or deposit requirements.
Not sure how your credit history may affect your mortgage options?
See our Bad Credit Mortgage service for a more detailed look at lender criteria, deposits, credit events and preparing an application.
How PBSbrokers Can Help
PBSbrokers can review your credit profile, income structure, and overall affordability to assess which mortgage options may realistically apply. This includes identifying suitable lenders and helping you understand what conditions to expect before moving forward.