If you’re applying for a mortgage in the UK, you’ve probably spent time thinking about your income, affordability, credit history, and deposit size. However, one part of the application process catches many buyers by surprise: proving the **source of deposit for mortgage** purposes.
UK lenders and conveyancing solicitors may need to understand where a buyer’s deposit comes from as part of their anti-money laundering, fraud prevention, and due diligence checks.
For many buyers, especially those with overseas assets, international financial histories, family-assisted deposits, or business income, source of deposit checks can become an important stage of the mortgage application.
The good news is that many legitimate deposit sources may be acceptable. The challenge is often not where the money came from, but whether you can provide sufficient evidence to support it.
In this guide, we’ll explain what source of deposit means, what counts as proof of deposit for a mortgage, the documents commonly required, and how buyers can prepare for a smoother mortgage journey.
What Does Source of Deposit Mean?
A source of deposit is evidence showing where the money used for your property deposit originated.
When a lender reviews your mortgage application, they are not simply checking whether you have enough money available. They may also need to understand how those funds were obtained and whether there is a clear financial trail supporting them.
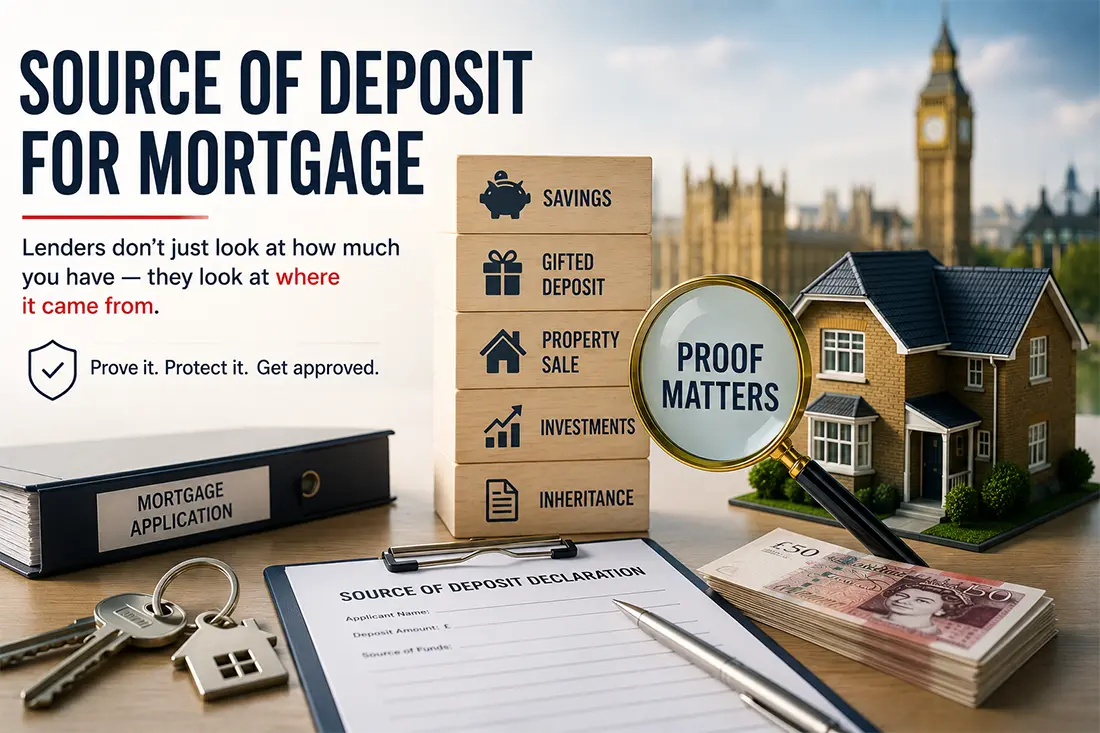
For example, your deposit may have come from:
– Personal savings
– A family gift
– The sale of a property
– Inheritance
– Investment proceeds
– Business profits
– Overseas assets
In simple terms, having the deposit available is only part of the process. Being able to explain and evidence where it came from can be equally important.
Why Mortgage Lenders Ask About the Source of Your Deposit
One of the most common questions buyers ask is why a lender needs information about money that already belongs to them.
The reason is largely connected to due diligence and anti-money laundering requirements. Property transactions can involve substantial sums of money, so lenders, banks, and solicitors may need to understand where funds have originated.
Lenders will typically want reassurance that:
– The deposit genuinely belongs to the applicant
– The money has come from a legitimate source
– The funds are not an undisclosed loan
– There are no concerns relating to fraud or financial crime
The exact checks and documents required will depend on the lender, solicitor, source of funds, and individual circumstances.
Source of Deposit vs Source of Funds
The terms **source of deposit** and **source of funds** are often confused. Although they are closely related, they are not always identical.
**Source of deposit** refers specifically to the money being used as the deposit for the property purchase.
**Source of funds** is broader and may refer to the wider money involved in the transaction, including the deposit and other purchase-related funds.
Because of this distinction, lenders and solicitors may ask questions about both. Understanding where your money came from and being able to provide a clear paper trail can help reduce unnecessary delays.
What Is Proof of Deposit for a Mortgage?
**Proof of deposit for a mortgage** refers to the documents used to show that you have the required deposit available and, where necessary, demonstrate where those funds came from.
Depending on your circumstances, proof of deposit may include:
– Bank statements
– Savings account statements
– Investment statements
– Property sale documents
– Inheritance documentation
– Gifted deposit letters
– Transfer confirmations
– Supporting evidence from the person providing a gift
It is useful to distinguish between simply showing that the money exists and proving its origin.
A bank statement showing a large balance may confirm that the money is currently available, but the lender or solicitor may still ask where that money originally came from.
Proof of Deposit for Mortgage: What Documents Are Usually Required?
Documentation requirements vary between lenders and individual circumstances, but certain records are commonly requested.
Personal savings
Bank and savings account statements may be used to demonstrate how funds have accumulated over time.
Where savings have built up gradually from employment income, the transaction history may help establish a clear financial trail.
Property sale proceeds
If your deposit comes from the sale of another property, you may be asked for documents such as:
– Completion statements
– Solicitor correspondence
– Bank statements showing receipt of the sale proceeds
Investments
Where funds come from investments, supporting evidence may include:
– Investment account statements
– Evidence of ownership
– Evidence showing the sale or disposal of the investment
– Bank statements showing where the proceeds were transferred
Inheritance
Inheritance funds may require documentation such as:
– Probate-related records
– Confirmation from the solicitor handling the estate
– Bank statements showing receipt of the money
Gifted deposits
When a family member is providing some or all of the deposit, lenders commonly request a gifted deposit letter together with supporting identification and source-of-funds evidence from the donor.
The purpose of these checks is to create a clear and understandable history for the deposit funds.
Do You Need Proof of Deposit for a Mortgage?
In most property purchases involving a mortgage, you should expect to provide evidence relating to your deposit.
However, the exact level of evidence required can vary considerably.
A straightforward deposit built up from salary savings may be relatively simple to demonstrate. A deposit involving overseas funds, investment sales, business income, property proceeds, or several family gifts may require significantly more documentation.
For this reason, it is worth organising your evidence before submitting a mortgage application rather than waiting for the lender or solicitor to request it.
Acceptable Sources of Deposit for a Mortgage
Many lenders may accept a range of deposit sources, provided the source is acceptable under their criteria and can be adequately evidenced.
Common examples include:
– Personal savings
– Gifted deposits
– Property sale proceeds
– Inheritance
– Investments
– Business-related income
– Overseas assets
Personal savings are often one of the simplest sources to evidence when the money has accumulated gradually and remained within identifiable accounts.
Property sale proceeds are also common, particularly for buyers moving home and using released equity towards their next purchase.
Business owners may be able to use certain business-related funds depending on their circumstances and lender criteria, although additional evidence may be required.
The key issue is usually not simply the type of deposit, but whether the lender and solicitor can understand and verify where the money came from.
A Source of Deposit for Mortgage Example
A practical example can help explain how this works.
Consider a buyer purchasing a residential property using funds from several sources:
– Part of the deposit comes from long-term employment savings
– Another portion comes from the sale of investments
– The remaining amount is gifted by the buyer’s parents
In this situation, supporting evidence might include:
– Savings account history
– Documentation confirming the investment sale
– A gifted deposit letter
– Evidence relating to the parents’ source of funds
If each part of the deposit can be clearly explained and evidenced, the application may be easier for the lender and solicitor to assess.
By contrast, unexplained transfers, undocumented cash deposits, or money moving repeatedly between several accounts may result in additional questions.
Gifted Deposits and Family Assistance
Gifted deposits are particularly common among first-time buyers.
A gifted deposit is typically money provided by another person, often a family member, without an expectation that it will be repaid.
Lenders commonly ask for written confirmation that:
– The funds are a genuine gift
– There is no repayment arrangement
– The donor will not normally acquire a financial interest in the property as a result of the gift
This is usually confirmed through a gifted deposit letter.
Depending on the lender and circumstances, the donor may also be asked to provide identification, bank statements, or evidence showing where their funds came from.
This can surprise buyers, but the lender or solicitor may need to understand the original source of gifted money as well as the transfer to the applicant.
Mortgage Deposits Coming from Overseas
Deposit funds originating outside the UK may be acceptable to lenders, but overseas funds can require additional checks and documentation.
Lenders and solicitors may need to understand:
– How the funds were accumulated
– Where the funds were held
– How the money was transferred
– Which accounts the money passed through
– Whether supporting records are available
The process can become more complex when funds have moved through several accounts or countries before reaching the UK.
Creating a clear timeline of transactions can therefore be extremely helpful.
Where overseas property sales, investments, or family gifts are involved, buyers should consider gathering documentation before beginning the mortgage application process
Source of Deposit Considerations for Iranian Buyers
Many Iranian buyers purchasing property in the UK have financial histories involving international transfers, overseas assets, family-supported deposits, or funds held outside the UK.
In these circumstances, preparation can become particularly important.
The challenge may not be proving that the money belongs to you. It may be demonstrating the route the funds have taken before arriving in the UK.
Supporting evidence may include:
– Bank statements
– Property sale documentation
– Investment records
– Transfer confirmations
– Employment records
– Family gift documentation
The earlier these records are collected, the easier it may be for a lender or solicitor to review the financial trail.
Buyers with more complex international circumstances may also benefit from speaking to a Persian-speaking mortgage broker familiar with UK mortgage applications involving international financial histories.
Common Mistakes That Delay Mortgage Applications
One common problem is moving money unnecessarily between multiple accounts shortly before applying for a mortgage.
There may be perfectly legitimate reasons for doing this, but every additional transfer can make the financial trail more complicated to explain.
Another common issue is failing to retain documentation relating to older transactions.
Buyers sometimes assume that because the money is legitimate, no further evidence will be required. However, lenders and solicitors may still need documentation before they can complete their checks.
Other potential issues include:
– Large unexplained transfers
– Missing older bank statements
– Mixing business and personal funds
– Incomplete gifted deposit documentation
– Overseas transactions without supporting evidence
In many cases, delays are caused not by the deposit source itself, but by gaps in the supporting documentation.
Special Considerations for Investors and SPV Mortgages
Investors purchasing buy-to-let property through a limited company may face additional questions about the source of their deposit.
For example, an applicant using an SPV may need to demonstrate both:
1. Where the deposit originally came from
2. How the funds entered the company
Where directors inject capital into the company, lenders may request documentation supporting the origin of those funds.
Different lenders have different criteria regarding company structures, acceptable deposit sources, and supporting evidence, so applicants should check the requirements that apply to their circumstances.
Can You Use a Source of Deposit for Mortgage Calculator?
Some buyers search for a **source of deposit for mortgage calculator** hoping to determine whether their deposit will satisfy lender requirements.
In practice, source-of-deposit checks cannot usually be reduced to a simple calculator.
Mortgage affordability calculations are largely numerical. Source-of-deposit assessments are different because they are primarily concerned with:
– Traceability
– Documentation
– The origin of funds
– The lender’s criteria
– Compliance checks
For this reason, reviewing the financial trail and supporting documents is generally more useful than relying on an automated calculator.
Frequently Asked Questions
What counts as proof of deposit for a mortgage?
Proof of deposit may include bank statements, savings statements, investment records, property sale documents, inheritance paperwork, gifted deposit documentation, or other records showing that the deposit is available and explaining where it came from.
How many months of bank statements are needed for proof of deposit?
There is no single requirement that applies to every mortgage application. The number of statements requested can depend on the lender, solicitor, type of deposit, and transaction history.
Can a mortgage deposit come from overseas?
Potentially, yes. However, overseas funds may require additional documentation explaining where the money came from and how it was transferred.
Can my family give me money for a mortgage deposit?
Gifted deposits from family members are commonly used, but the lender will usually have specific requirements regarding the gift and the evidence provided by the donor.
Why do banks require a deposit for a mortgage?
A deposit reduces the proportion of the property’s value being financed by the lender and provides the buyer with equity in the property from the outset. The deposit amount required depends on the mortgage product, lender criteria, property, and applicant circumstances.
Final Thoughts
Source of deposit checks are a normal part of many UK mortgage applications.
Whether your deposit comes from savings, investments, inheritance, family gifts, business income, property sale proceeds, or overseas assets, the important issue is usually whether the funds can be clearly explained and supported by appropriate documentation.
Preparing evidence early, maintaining organised financial records, and avoiding unnecessary movement of money between accounts can help reduce delays during the mortgage process.
If your deposit involves overseas assets, complex transfers, gifted funds, or business income, getting advice before submitting the application may help identify potential issues earlier.
Disclaimer: This article is for general information purposes only and should not be considered mortgage, legal, tax, or financial advice. Mortgage lender criteria, anti-money laundering requirements, and source of deposit verification processes vary between lenders and individual circumstances. Always seek professional advice from a qualified mortgage broker, solicitor, accountant, or financial adviser before making decisions relating to property purchases or mortgage applications.